- Finance Broking Services for New Farm Residents
Mortgage Broker for New Farm Buyers and Homeowners
Write Finance helps New Farm buyers, homeowners and investors compare home loans, refinancing and investment lending options. We review your income, deposit and existing commitments, explain lender requirements and support your application through to settlement.
Your Local Finance Broker
Helping New Farm Residents Borrow with Confidence
Finance Broking
Home Loans
We compare owner-occupied home loans for New Farm houses, townhomes and apartments based on your income, deposit and existing commitments. We explain rates, fees, repayment options and relevant property requirements. Approval remains subject to lender assessment and valuation.
Refinancing
We compare your current home loan with relevant refinancing options, including rates, fees, features and remaining loan term. Switching costs and any fixed-rate break costs are included in the review. A lower repayment does not always mean a lower total borrowing cost.
Property Investment Loans
We compare investment lending options based on your income, deposit, existing commitments and proposed purchase. We explain loan features, repayments, costs and lender requirements. Your accountant, solicitor and licensed financial adviser advise on tax, ownership structure and investment suitability. With your permission, we coordinate the lending application with them.
We Help New Farm Clients Who Want To:
- Buy an owner-occupied home in New Farm
- Compare refinancing options for a New Farm apartment or house
- Review whether equity may be available for a proposed purchase or renovation
- Purchase an investment property close to the Brisbane CBD
- Compare lenders’ requirements for an inner-city apartment
- How We Assess Your Borrowing Position
We start with your purchase or refinance plans, income, deposit and existing commitments. We explain how lenders may assess your circumstances and the proposed property.
We help organise the income and financial documents required for your circumstances. For self-employed borrowers, this may include tax returns, BAS and business financial statements.
We compare lender assessments using your income, expenses and existing commitments to estimate your borrowing range. Estimates are indicative and subject to lender assessment and approval.
Lenders differ in how they assess income, expenses and property security. We compare relevant policies across our lender panel to identify options that may suit your circumstances.
If your current borrowing estimate does not meet your plans, we explain factors you may be able to review, such as existing commitments, deposit savings and supporting documents. Any changes remain subject to lender assessment and do not guarantee a higher borrowing limit or approval.
- Over 60 Lenders
Access to Australia’s Leading Lenders
We compare relevant options from our panel of banks, non-bank lenders and specialist providers. We explain rates, fees, features and trade-offs against your circumstances and goals. Our panel does not include every lender or product in the market.
Making home loans simpler for New Farm borrowers.
Why New Farm Homeowners Choose Write Finance
We help New Farm buyers, homeowners and investors understand the lending requirements for their circumstances and proposed property.
Our support covers:
- Apartment purchases, including lender requirements for unit size, building type and valuation
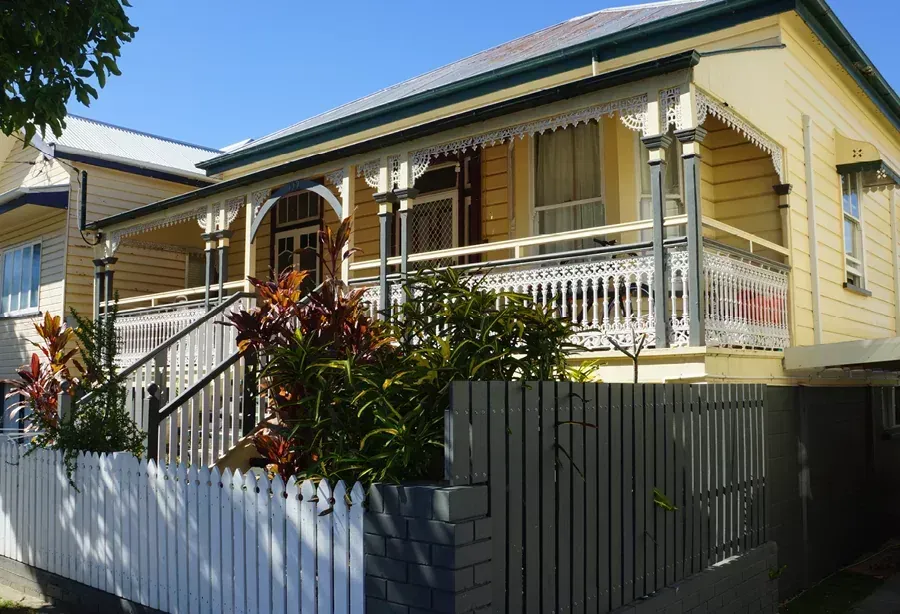
- Purchases or renovations of older homes, including relevant property documentation
- Refinancing comparisons, including rates, fees, switching costs and remaining loan term
- Applications with self-employed income and supporting business records
You’ll work with Mark Tran to compare relevant options and prepare your application. Approval remains subject to lender assessment and valuation. With your permission, we coordinate with your accountant, solicitor or licensed financial adviser where relevant. Your solicitor or conveyancer advises on contract conditions, planning restrictions and legal requirements.
What You Get with Write Finance
Your lending needs depend on your income, commitments and plans. We help New Farm buyers, homeowners, investors and business owners compare options, understand lender requirements and prepare their applications.
We review your income, deposit, existing commitments and proposed loan purpose, then explain relevant options, costs and repayment requirements.
Lending support for borrowers in New Farm, Teneriffe, Fortitude Valley and Brisbane CBD, available by phone or video, or in person where practical.
We compare relevant options from banks, non-bank lenders and specialist providers on our panel, subject to their lending requirements. Our panel does not include every lender or product in the market.
We explain repayment options and features such as offset accounts and split loans, including their costs, eligibility requirements and trade-offs.
We help prepare your documents, coordinate lender valuation requests and keep you informed through application and settlement.
Illustrative Borrower Scenarios
Two examples of how we approach home lending enquiries in New Farm.
Buying a New Farm Apartment
A buyer considering a New Farm apartment needs to understand whether the building and unit suit lender requirements. We review the proposed unit, deposit and income, and clarify any lender conditions relating to floor area, building type or valuation.
Refinancing Before Renovating
A New Farm homeowner plans to refinance before renovating an older home. We review equity, quotes, project scope and repayments, then compare standard equity release with construction lending where relevant.
These examples illustrate the assessment process. They are not client outcomes. Available lending depends on your circumstances and lender assessment.
Frequently Asked Questions
Lenders assess your income, expenses, deposit and existing commitments alongside the proposed property. For apartments, requirements may depend on internal floor area, building type, use and valuation. For older homes, lenders may request additional property information. Requirements vary by lender and loan product. We explain those relevant to the options being considered.
Lending may be available depending on your financial position and the apartment’s characteristics. Lenders may consider internal floor area, building type, property use and valuation. Minimum sizes and other conditions vary by lender and product. We review the proposed unit and compare relevant options before you apply. Approval remains subject to lender assessment.
Yes. Self-employed borrowers can apply for home loans in New Farm, subject to lender assessment. Your options depend on your income, trading history, deposit, existing debts and the property you intend to buy.
We review your business and personal income documents and compare lender policies to find options suited to your circumstances.
The property’s condition, valuation and proposed renovations may affect lender requirements. Additional documentation may be requested where heritage listings, character overlays or building work are relevant. We explain the lending requirements for the options being considered. Your solicitor or conveyancer advises on planning restrictions, approvals and contract conditions. Pre-approval is conditional and does not guarantee final approval.
Your deposit requirement depends on the lender, property, loan product and your circumstances. Allow for purchase costs as well as the deposit. We explain available options, any lenders mortgage insurance and government support that may apply under current rules. Guarantor arrangements involve risks for the guarantor and require careful consideration and independent legal advice.
We compare your current loan with relevant refinancing options, including rates, fees, features and the remaining term. The comparison includes switching costs and any fixed-rate break costs, with repayments and total costs considered over a consistent period. Accessing equity increases your debt and may place your property at risk if used as security. A lower repayment does not always mean a lower total borrowing cost.