- Toowoomba finance broker for self employed home loans
Your Toowoomba finance broker for self-employed home loans
Tailored lending strategies for Toowoomba business owners, sole traders, contractors, farmers, and company directors who need lending that properly reflects their true financial position.
Why Self-Employed Borrowers in Toowoomba Choose Write Finance.
Self-employed lending is different across Toowoomba. Regional fluctuations, seasonal income, agricultural cycles, and mixed PAYG/ABN income mean traditional lenders often misread your real capacity. We specialise in structuring home loans that reflect how you actually earn, not just what appears on paper.
- Lending designed around variable and seasonal income
- Support for complex income structures (trusts, companies, contractors)
- Clear explanation of what lenders need and how to strengthen your file
- Refinancing to improve cash flow, consolidate business debt, or reduce repayments.
- Access to over 60 lenders who work well with self-employed clients
- Our Expertise in Self-Employed Lending
Strategic Lending Advice
Practical, grounded lending guidance for Toowoomba business owners with variable or seasonal income. We clarify how lenders interpret your financials so your true borrowing capacity is assessed accurately.
Toowoomba Market Insight
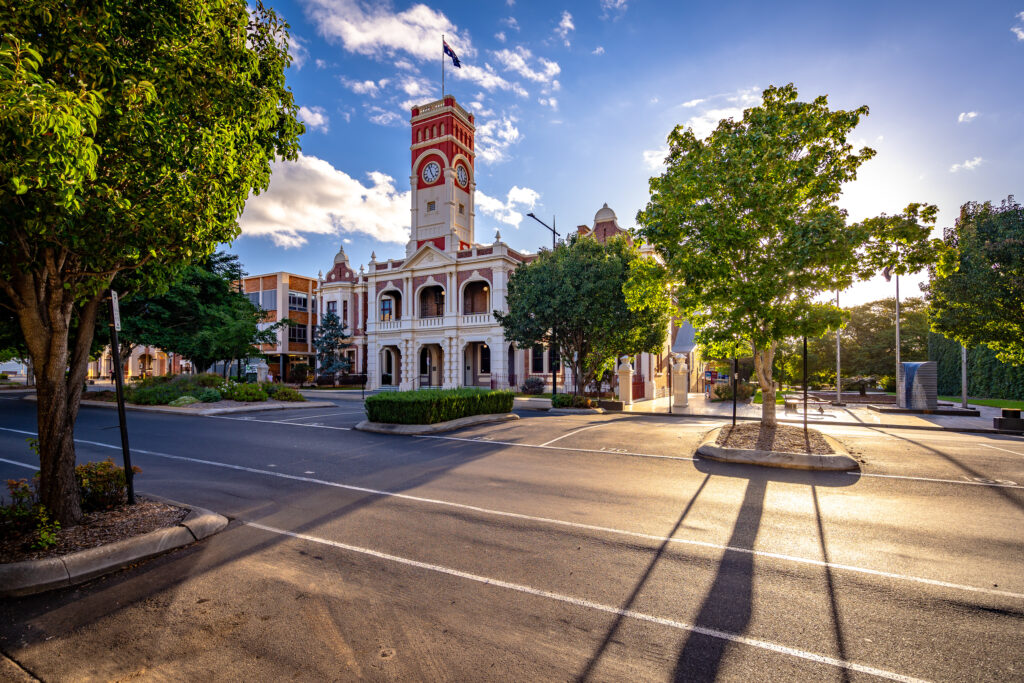
From East Toowoomba and Mount Lofty to Highfields, Glenvale, and the wider Darling Downs, we understand local property trends, semi-rural postcode variations, and regional lending appetite across the area.
Lender Access for Self Employed Borrowers
With access to over 60 lenders including self-employed specialists we find options that suit your income structure, business setup, and documentation, giving you greater flexibility and a stronger lending match.
Business-Led Planning
Your loan strategy is built around your business performance, cash flow, and long-term plans — not a bank template. We help you borrow confidently while protecting stability as your business evolves.
Documentation Support
We prepare the paperwork lenders want to see — BAS, P&L, business bank statements, financials, and supporting documents — packaged clearly to strengthen your approval position and reduce lender questions.
- Over 60 Lenders
Access to Australia’s Leading Lenders
We compare options across banks, non-banks, and specialist lenders to find solutions that suit regional business owners, agricultural operators, and local Toowoomba industries.
- Our Capabilities
Specialist Lending Support for Toowoomba Business Owners
Self-Employed Home Loans
Whether your income comes through a business, trust, multiple contracts, seasonal farm revenue, or a mix of sources, we match you with lenders who understand complex income. We package BAS, financials, and business records so lenders see the full picture clearly.
Business Owner Refinancing
We review your existing loans, rates, fees, features and remaining terms against available refinancing options. We explain switching costs, any fixed-rate break costs and the risks of consolidating debts or using property as security. A lower repayment does not always mean a lower total borrowing cost.
Property Investment Loans
We compare investment lending options based on your income, deposit, existing commitments and proposed purchase. We explain loan features, repayments, costs and relevant lender requirements. Your accountant, solicitor and licensed financial adviser advise on tax, ownership structure and investment suitability. With your permission, we coordinate the lending application with them.
Types of Self-Employed Clients We Work With
Toowoomba’s business community is diverse, and income often doesn’t follow a simple pattern. We support a wide range of self-employed clients across Toowoomba and the Darling Downs, including:
Sole Traders
Tradies, café owners, creatives, personal trainers, beauty therapists, and small business operators working under their own ABN.
Company Directors
Owners drawing income through salary, dividends, trust distributions, retained earnings, or director loans.
Contractors & Subcontractors
Electricians, carpenters, plumbers, IT contractors, transport operators, and project-based workers with variable income.
Partnerships
Businesses with shared income structures where clarity is needed for lender assessment.
Trust Structures
We support borrowers whose income comes through family, unit or business trusts. We review trust documents, distributions and business records against lender requirements. Your accountant and solicitor advise on tax, ownership and legal matters.
Side Hustle & Multi-Income Earners
Toowoomba locals balancing PAYG roles with ABN contracting, rental income, short-term projects, or seasonal work.
Our process
01.
Understanding You
Everything begins with a conversation no assumptions, no generic lending paths. We learn how your Toowoomba business earns: contracts, seasonal cycles, farm revenue, ABN work, director drawings, or multiple income streams.
We also make sure your lending goals align with the right lender structure whether you prefer major banks or specialist self-employed lenders.
02.
Assessing Your Position
Self-employed income doesn’t fit neatly on a payslip. We review financials, BAS, farm records, business bank statements, and any income fluctuations that need explanation.
For Toowoomba clients, we also consider regional property values, postcode variations, and lender appetite for rural and semi-rural locations.
03.
Planning and Matching
We compare relevant lender policies, rates, fees and loan features against your business income, financial commitments and property goals. We explain available options and trade-offs. Where tax or ownership considerations affect the proposed lending, we coordinate with your accountant and qualified advisers with your permission.
04.
Ongoing Support
Our support continues beyond settlement with proactive check-ins, regular updates and an annual lending review. We can also review your lending when your income, business, personal circumstances or fixed-rate period changes.
Why us
Why Toowoomba Business Owners Choose Write Finance
Write Finance is trusted by business owners, tradies, contractors, farmers, and regional professionals who want lending advice grounded in real numbers, not guesswork. We take the time to understand your business, analyse your financials properly, and match you with lenders who see more than just tax-reduced income.
Every recommendation is grounded in strategy, not sales. You’ll speak directly with senior finance broker Mark Tran, who specialises in self-employed lending, understands the challenges Toowoomba business owners face, and provides clear, personalised guidance from the first call through to settlement. Write Finance operates under LMG Broker Services Pty Ltd (ACL 517192), giving you the confidence of full compliance and a service approach built on transparency, clarity, and long-term support.
Finance around your goals
Lending guidance shaped around your income, circumstances and plans.
Compare lending options
Explore loan options based on lender policies, costs and features.
Support through the process
Help with documentation, applications and lender communication through to settlement.
Income Types Banks Accept
Banks assess self-employed income differently from PAYG applicants. Instead of relying on a single payslip, lenders look at multiple income sources, business structures, and supporting documents to determine your true borrowing capacity. We help Toowoomba business owners present these income types clearly, so lenders see the full picture not just the surface numbers.
Sole Trader Income
Lenders review your tax returns, BAS statements, profit-and-loss reports, and business bank statements to confirm stable income, allowable addbacks, and overall consistency in earnings.
Contractor & Subcontractor Income
Documentation requirements for ABN contractors and subcontractors vary by lender and loan type. We review your trading history, contracts, income records and existing commitments, then explain the evidence required for your application. A shorter trading history may limit available options.
Multiple Income Streams
If your income comes from contracts, PAYG work, farming, a family business, a trust, or side ventures, we structure your application so lenders clearly understand how each income stream fits together.
Company Director Income
Lenders may assess salary, dividends and business profits, depending on your ownership, access to income and the lender’s policies. Required reporting periods and treatment of retained earnings vary. We review your personal and business records and explain the evidence required for the options being considered.
Trust Distributions
Income paid through a family, unit, or business trust is reviewed alongside business performance and your role within the trust to determine how much income can be counted toward borrowing capacity.
Retained Profits & Addbacks
Some lenders allow addbacks for depreciation, one-off expenses, interest adjustments, or business-related addbacks that can increase your assessed borrowing capacity.
Verification Documents
Lenders assess self-employed income very differently from PAYG applicants. Having the right documentation prepared and presented clearly can significantly strengthen your approval position. These are the documents we help Toowoomba business owners prepare before applying for a self-employed home loan.
Tax Returns & Financial Statements
Required financial records depend on the lender, loan type and your circumstances. These may include personal and business tax returns, notices of assessment and business financial statements. We explain the reporting periods and supporting evidence required for the options being considered.
BAS Statements
For borrowers with newer trading histories or fluctuating income, BAS statements help demonstrate real-time revenue, quarterly performance, and business activity levels especially useful for contractors, small business owners, and rural operators.
Profit & Loss Reports
A current profit-and-loss report helps explain revenue, expenses and seasonal changes in business performance. Lenders may require it alongside tax returns, bank statements and other records. Any income adjustments depend on lender policy and supporting evidence.
Business Bank Statements
Bank statements confirm consistent cash flow, business activity, spending patterns, and how income actually moves through your accounts.
Accountant Declarations
Some lenders accept accountant letters to verify income, clarify complex structures, confirm recent performance, or explain adjustments not visible in standard financials.
Trust & Company Documents
If you trade through a family trust, company, or partnership, lenders may request trust deeds, constitutions, distribution statements, or ASIC records to verify ownership, roles, and income flow.
Invoices & Contract History (for contractors)
Contractors, trades, freelancers, and subcontractors may use recent invoices, remittance summaries, job sheets, or contract agreements to prove consistent demand, workload, and income stability.
Testimonials
What Our Clients Say
Real feedback from Toowoomba business owners and self-employed clients who’ve partnered with Write Finance.
Toowoomba FAQs
Seasonal, agricultural or project-based income can require more detailed assessment than a regular salary. Lenders review income history, business expenses, existing commitments and supporting records. We help explain fluctuations and compare relevant lender policies. Clear records support assessment but do not guarantee additional borrowing capacity or approval.
Required documents depend on your business structure, trading history, lender and loan product. They may include personal and business tax returns, notices of assessment, financial statements, BAS and bank statements. Contractors and agricultural operators may need additional income records. We confirm the reporting periods and supporting evidence required for the options being considered.
Alternative-documentation lending may allow eligible self-employed applicants to provide lender-approved income evidence such as BAS, business bank statements or an accountant’s declaration. It still requires income verification and assessment. Eligibility, rates, fees, deposit requirements and available products vary by lender. We explain the requirements and costs before you decide.
Applicants with a shorter trading history can enquire, but available options depend on the lender, loan type and supporting evidence. We review your industry experience, current financial performance and available documents before discussing possible pathways. A shorter trading history may limit your options, and approval remains subject to lender assessment.
Options may include home purchase, investment, construction and refinancing loans, with alternative-documentation products available to eligible applicants. We compare rates, fees, features, repayment types and documentation requirements against your circumstances. Available options depend on your financial position, the property and lender assessment.
Keep your financial records current and ensure your tax returns, BAS and bank statements accurately show business income and expenses. Lenders also assess credit history, debts, living expenses, deposit and trading history. We review your records and explain any gaps before applying. Clear documentation supports assessment but does not guarantee approval.
Government grants, deposit schemes and concessions may be available to eligible first-home buyers, including self-employed applicants. Eligibility depends on current program rules, your circumstances and the property. We help explain which options may apply to your lending plans and the supporting information required. Check current requirements with the administering authority before committing to a purchase.
Toowoomba buyers may qualify for government support depending on current program rules, buyer circumstances and the proposed property. Grants, deposit schemes and transfer duty concessions have different requirements. We help explain how relevant support could fit into your home loan plans. Confirm eligibility and any ongoing obligations with the administering authority and your solicitor.
Meet Your Finance Broking Team in Toowoomba
We’re small, personal, and committed to your success.
How Write Finance Helps
How We Assess Your Self-Employed Borrowing Position
Discovery and Goal Setting
We start by understanding your goals — whether you’re buying your first home, upgrading, investing in Toowoomba’s fast-growing suburbs, or refinancing to improve cash flow. For self-employed borrowers, we look deeper into how your income is earned, whether through a company, trust, contractor income, or multiple revenue streams. This allows us to present your position to lenders in the most accurate and favourable way.
Documentation and Preparation
We provide a document checklist based on your business structure and relevant lender requirements. This may include tax returns, financial statements, BAS, business bank statements and other supporting records. We check for gaps and help present your income clearly. Complete documentation supports assessment but does not guarantee approval.
Borrowing Capacity Assessment
We use lender-specific assessment tools to estimate your borrowing position based on income, expenses and existing commitments. For business owners, we review financial records and any income adjustments permitted by the relevant lender. Estimates are indicative, remain subject to verification and lender assessment, and are not loan approval.
Lender Comparison and Recommendation
Every lender assesses self-employed borrowers differently. We compare policies and outcomes from more than 60 lenders, identifying where you can borrow effectively without sacrificing favourable terms. This includes identifying lenders who: Accept your structure (company, trust, or sole trader) Understand variable or seasonal income patterns Offer flexible documentation pathways (alt-doc / low-doc where appropriate) Support your Toowoomba property goals You receive a clear recommendation based on structure, strategy, and long-term suitability — not just the interest rate.
Preparing Your Borrowing Position
If further preparation is needed, we explain practical steps such as reviewing existing debts, building savings and gathering complete income records. Changes to how business income is drawn or your financial structure should be discussed with your accountant and qualified advisers. These steps do not guarantee increased borrowing capacity or approval.
Suburbs Supported Across Toowoomba
We support self-employed clients and business owners across the entire Toowoomba region, from the urban centre to the surrounding rural communities and fast-growing satellite towns.
Toowoomba CBD & Central Suburbs
- Toowoomba City
- East Toowoomba
- South Toowoomba
- North Toowoomba
- Newtown
- Mount Lofty
- Centenary Heights
- Harristown
- Kearneys Spring
- Middle Ridge
Northern Toowoomba Region
- Highfields
- Cabarlah
- Meringandan
- Meringandan West
- Goombungee
- Crows Nest
- Blue Mountain Heights
- Birnam
- Kleinton
Western Toowoomba & Surrounds
- Wellcamp
- Torrington
- Wilsonton
- Wilsonton Heights
- Cranley
- Glenvale
- Charlton
- Kingsthorpe
- Oakey
- Gowrie Mountain
Southern Toowoomba Region
- Darling Heights
- Drayton
- Top Camp
- Preston
- Hodgson Vale
- Vale View
- Westbrook
- Wyreema
Eastern Toowoomba & Lockyer Border
- Withcott
- Helidon
- Helidon Spa
- Murphy’s Creek
- Postmans Ridge
- Prince Henry Heights
- Redwood
- Rangeville
Ready to move forward with your loan?
Share a few details and we’ll get back to you to book a time that works.
We’ll talk through your goals, your business income, and the lending pathways available to you.
No cost. No obligation. Just clear guidance tailored to your business income.